A Debt Collector Keeps Calling Me. What Am I Allowed to Do?
Debt collector keeps calling you? Learn how to ask for debt validation, limit contact in writing, spot scams, and file a CFPB complaint if rules are broken.
“Nearly re-enrolled in English class while reading a lease.”
Theology · Scripture Cards
Open a scripture card
Already read and shared by 315 people.
 Daughter, Your Faith Has Healed You
Mark 5:34
He said to her, “Daughter, your faith has made you well. Go in peace, and be cured of your disease.”
Read this card
 While He Was Still a Long Way Off
Luke 15:20, 22
“He arose and came to his father. But while he was still far off, his father saw him and was moved with compassion, and ran, fell on his…
Read this card
 The Rainbow Covenant
Genesis 9:13, 16
I set my rainbow in the cloud, and it will be a sign of a covenant between me and the earth. … The rainbow will be in the cloud. I will…
Read this card
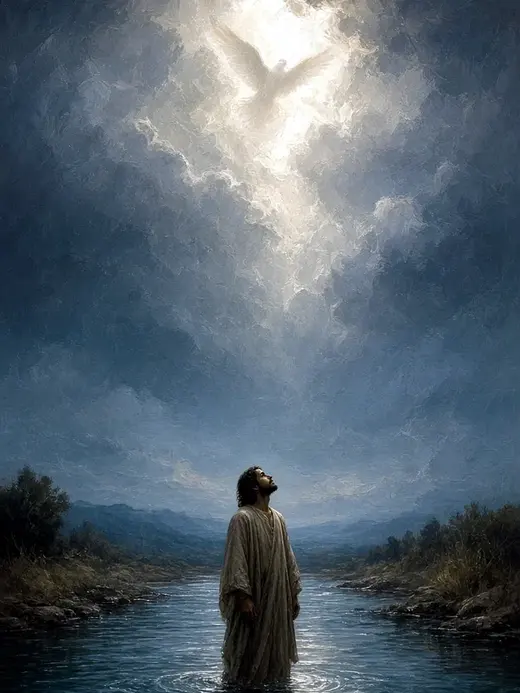 This Is My Beloved Son
Matthew 3:16-17
Jesus, when he was baptized, went up directly from the water: and behold, the heavens were opened to him. He saw the Spirit of God…
Read this card
 Bread from Heaven
Exodus 16:4
Then Yahweh said to Moses, “Behold, I will rain bread from the sky for you, and the people shall go out and gather a day’s portion every…
Read this card
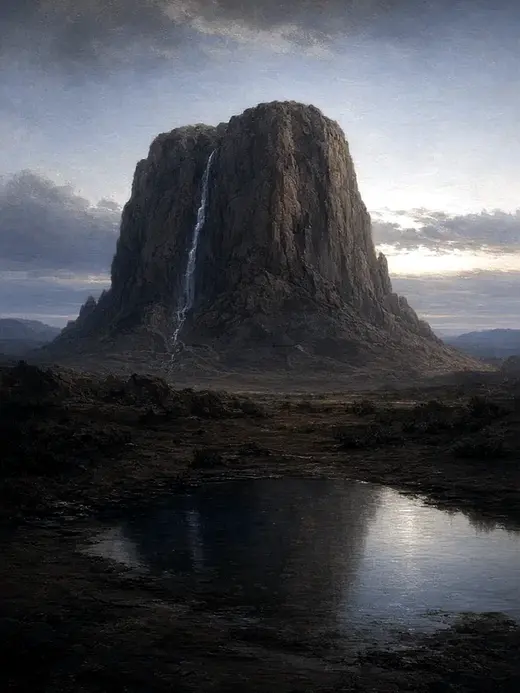 Water from the Rock
Exodus 17:6
Behold, I will stand before you there on the rock in Horeb. You shall strike the rock, and water will come out of it, that the people may…
Read this card
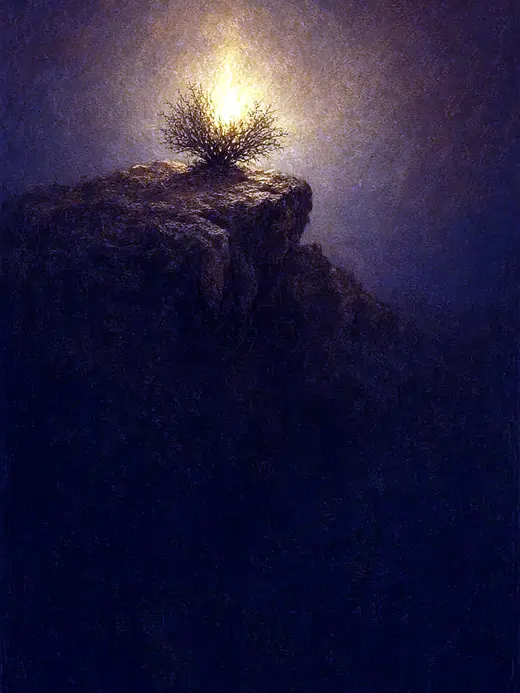 I AM WHO I AM
Exodus 3:14
God said to Moses, “I AM WHO I AM,” and he said, “You shall tell the children of Israel this: ‘I AM has sent me to you.’ ”
Read this card
 He Is Not Here, He Has Risen
Matthew 28:5-6
The angel answered the women, “Don’t be afraid, for I know that you seek Jesus, who has been crucified. He is not here, for he has risen…
Read this card
Key Takeaways
- Verify the collector before paying anything, and never give account info to an incoming caller.
- Use the CFPB's sample letters to dispute a debt or limit contact in writing.
- Keep a call log, never ignore court papers, and report violations to the CFPB.
General information, not legal advice. Rules vary by state and can change; check the official sources linked in this guide.
Unknown number. Again. You let it ring out, and then a voicemail shows up saying something about "an important business matter." If a debt collector keeps calling you, your stomach probably drops every time your phone buzzes. Mine did.
Here's the thing I wish someone had told me sooner: you have rights in this situation, and the federal government literally publishes free letters you can use. This is general information, not legal advice, but it's a solid place to start.
First: is this even a real debt collector?
Debt scams are common. Before you pay anything, slow down. Real collectors should be able to tell you who they are, who they're collecting for, and how much they say you owe. Scammers often push for instant payment by gift card, wire, or a payment app, and they love urgency.
Never confirm your full Social Security number or bank details to an incoming caller. Hang up, find the company's contact info yourself, and call back if you need to. That pause alone kills a lot of scams, because urgency is a classic lever from Cialdini's principles of persuasion: scarcity and pressure make people act before thinking.
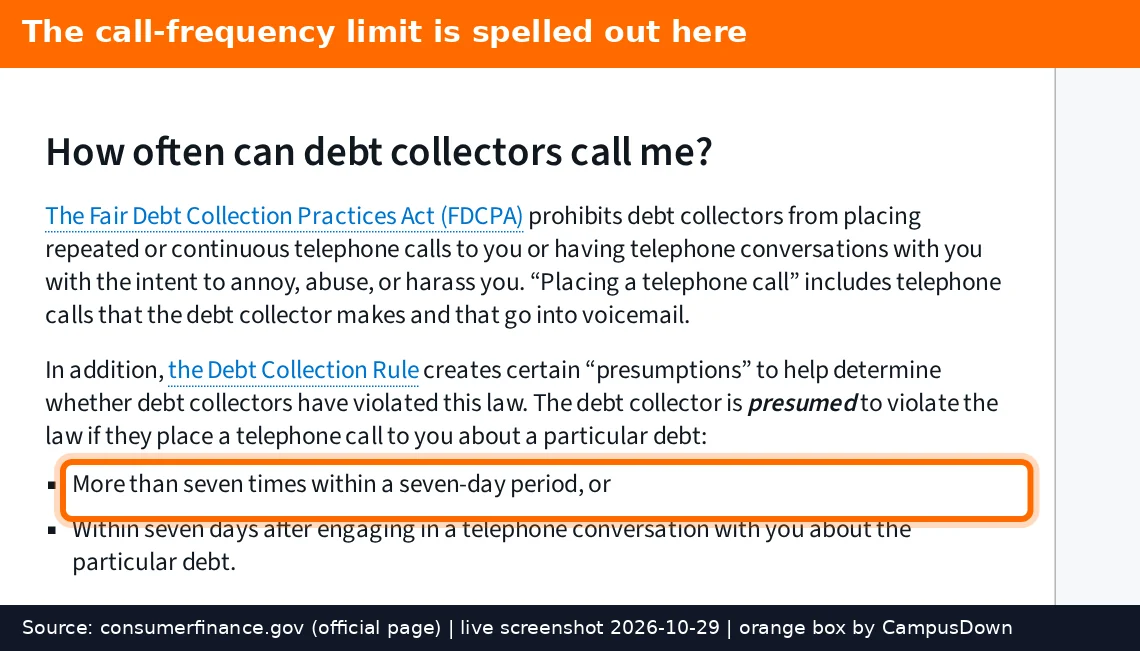
The Consumer Financial Protection Bureau keeps a debt collection help center with answers, your rights, and sample letters you can adapt. That page is the backbone of this guide.
Ask them to prove it (debt validation)
Under federal law, debt collectors generally have to give you certain information about the debt, like the amount and the creditor. If you don't recognize the debt, or the amount looks wrong, you can dispute it in writing. Doing it quickly matters, because some protections are tied to a time window after you get the collector's validation information.
The CFPB has sample letters for exactly this. Keep it short and factual. Don't admit the debt is yours if you're not sure. Keep a copy, and send it in a way you can prove.
You can limit how they contact you
You don't have to live on their schedule. Under the federal debt collection rules:
- Collectors generally can't call at times they know are inconvenient for you. Calls before 8 a.m. or after 9 p.m. your time are generally presumed inconvenient.
- If you tell them in writing that your employer doesn't allow calls at work, they're generally supposed to stop calling you there.
- You can ask in writing that they stop contacting you, or contact you only in a certain way. Stopping contact doesn't erase a real debt, though, and they may still take other legal steps.
What they generally can't do
Debt collectors are generally not allowed to harass you, use threats of violence, use obscene language, or lie, like pretending to be a lawyer or police officer, or threatening arrest. They also generally can't tell your coworkers or friends about your debt.
There's a reason this feels so personal. It plays on the spotlight effect: we assume everyone can see our money problems. They can't. Plenty of people deal with collections at some point, and it says nothing about who you are.
If they break the rules
You can submit a complaint to the CFPB online, and you can also contact your state attorney general. Your call log, letters, and voicemails all help. If you're served with a lawsuit or the debt is large, free legal aid organizations and law school clinics can help you look at your options, including whether the debt is too old to sue on in your state.
It's also worth checking your credit score and reports (free at AnnualCreditReport.com) to see what's actually listed under your name.
Need a different letter for a related problem? The complaint letter templates hub has them all in one place, including a copy-paste consumer complaint letter.
Legal stuff is easier with a friend. Send this to someone who could use it.
Pick an app — it just sends the link, nothing else.
Frequently Asked Questions
Can a debt collector keep calling me every day?
Collectors can't harass you, and federal rules limit how often and when they call. Calls before 8 a.m. or after 9 p.m. are generally presumed inconvenient. You can also ask in writing to limit contact.
How do I make a debt collector prove I owe the debt?
Dispute the debt in writing and ask for validation. The CFPB publishes sample letters you can adapt. Do it quickly, since some rights are tied to a time window.
Will telling a collector to stop calling erase my debt?
No. It limits contact, but a valid debt may still exist, and the collector could take other legal steps like filing a lawsuit.
Where do I report a debt collector breaking the rules?
You can submit a complaint to the CFPB and contact your state attorney general. Keep records of every call and letter. This is general information, not legal advice.