Should I Take Out a Payday Loan as a College Student? My Honest Breakdown
Should you take out a payday loan as a college student? Learn how payday loans work, why rollovers get expensive, state rules, and safer options on campus.
“Nearly re-enrolled in English class while reading a lease.”
Theology · Scripture Cards
Open a scripture card
Already read and shared by 315 people.
 Daughter, Your Faith Has Healed You
Mark 5:34
He said to her, “Daughter, your faith has made you well. Go in peace, and be cured of your disease.”
Read this card
 Today a Savior Is Born
Luke 2:10-11
The angel said to them, “Don’t be afraid, for behold, I bring you good news of great joy which will be to all the people. For there is born…
Read this card
 Surely I Will Be with You
Judges 6:16
Yahweh said to him, “Surely I will be with you, and you shall strike the Midianites as one man.”
Read this card
 He Is Not Here, He Has Risen
Matthew 28:5-6
The angel answered the women, “Don’t be afraid, for I know that you seek Jesus, who has been crucified. He is not here, for he has risen…
Read this card
 This Is My Beloved Son
Matthew 3:16-17
Jesus, when he was baptized, went up directly from the water: and behold, the heavens were opened to him. He saw the Spirit of God…
Read this card
 Your Faith Has Made You Well
Mark 10:52
Jesus said to him, “Go your way. Your faith has made you well.” Immediately he received his sight and followed Jesus on the way.
Read this card
 A Fourth Walking in the Fire
Daniel 3:25
He answered, “Look, I see four men loose, walking in the middle of the fire, and they are unharmed. The appearance of the fourth is like a…
Read this card
 God Shut the Lions’ Mouths
Daniel 6:22
My God has sent his angel, and has shut the lions’ mouths, and they have not hurt me, because innocence was found in me before him; and…
Read this card
Key Takeaways
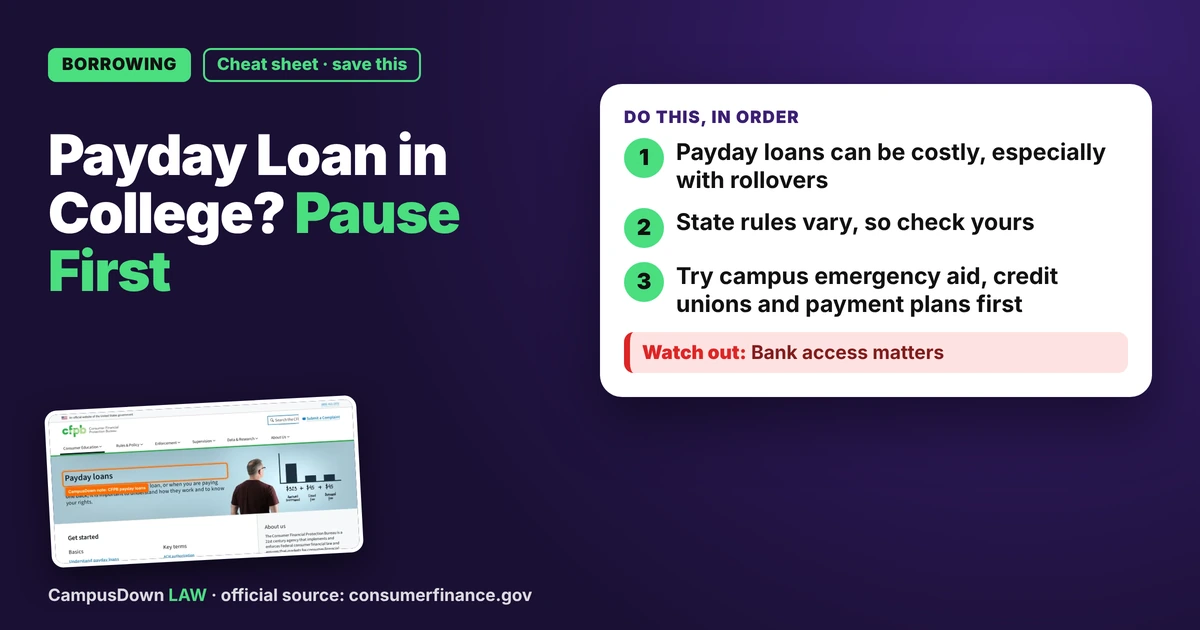
- Payday loans can be costly, especially with rollovers.
- State rules vary, so check yours.
- Try campus emergency aid, credit unions and payment plans first.
General information, not legal advice. Rules vary by state and can change; check the official sources linked in this guide.
Rent due Friday, paycheck the Friday after. The math isn't mathing. A payday lender ad pops up promising cash today, no credit check. So the question in my search bar was should I take out a payday loan as a college student. I went down the rabbit hole so you can skip it.
Not a lawyer or a financial advisor. Just a student who has eaten a lot of rice this semester. General info only.
How payday loans generally work
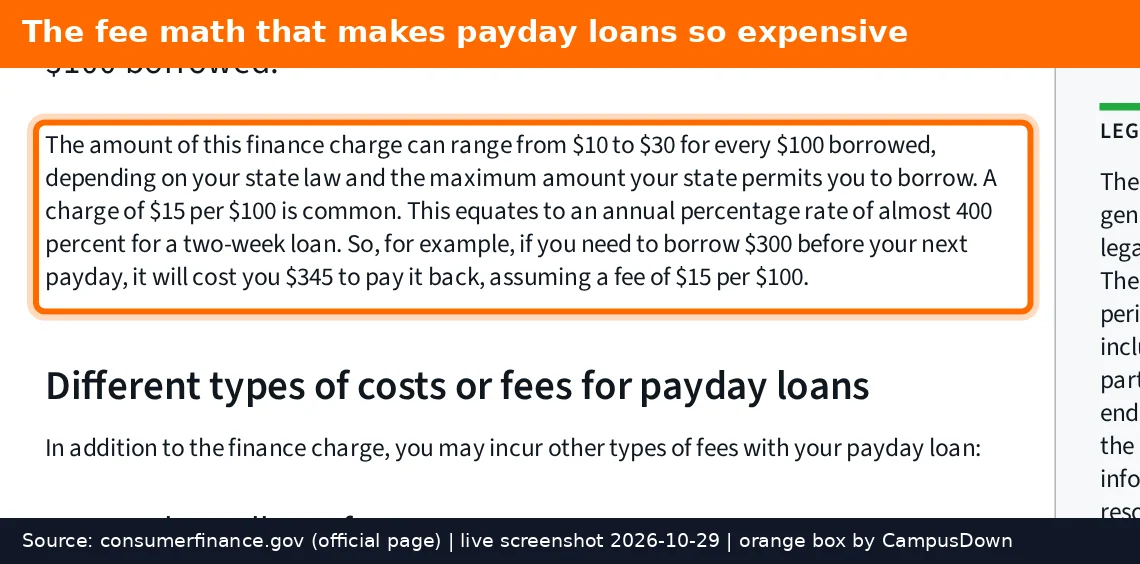
A payday loan is usually a small, short-term loan meant to be repaid on your next payday, often in one lump sum. You might give the lender access to your bank account or a post-dated check. The cost is typically a fee per amount borrowed, and when you turn that fee into an annual rate, it can be very high compared to a credit card or a personal loan.
The CFPB's payday loans page explains how these loans work, what to watch out for and how to submit a complaint.
Where it goes sideways: rollovers
If you can't pay the full amount on payday, some lenders let you roll it over or take a new loan, paying another fee. That's how a short-term fix turns into a months-long fee loop. It's the sunk cost feeling plus loss aversion: you've already paid fees, so you keep paying to avoid "losing" what you put in.
State rules vary a lot
Some states ban or heavily limit payday loans, while others allow them with rules on fees, loan size or rollovers. Online lenders don't get to ignore your state's rules just because they're online, but enforcement is complicated. Check your state attorney general or financial regulator site before borrowing.
Safer options to check first
Before a payday loan, I'd try these, roughly in this order. Your financial aid office may have emergency grants or short-term loans for students, and many schools have them specifically for rent gaps. The dean of students office sometimes has emergency funds too. Credit unions often offer small-dollar loans with lower costs, and some have student-friendly accounts. Talking to your landlord about a short payment plan in writing can buy you a week. Your employer might offer a pay advance. And local or campus food pantries can free up grocery money for rent.
There's also the CFPB's rental help resources if the bigger problem is rent itself.
Why it's so tempting
Hyperbolic discounting makes money now feel way more valuable than money later. Payday ads are built around that: fast, easy, today. Knowing it doesn't make you immune, but it does give you a second to pause.
If you already have one
Read the agreement and know the due date and fees. Ask the lender about extended payment plans, which some states require lenders to offer. If you think the lender is breaking rules, like taking unauthorized withdrawals, contact your bank and submit a complaint to the CFPB or your state regulator. Free legal aid can also help.
And I canceled my plan to "treat myself" that weekend. The only thing I'm treating myself to is a functional bank balance.
Found this helpful? Share it with a friend who needs it.
Pick an app — it just sends the link, nothing else.
Frequently Asked Questions
Are payday loans a good idea for students?
They're often expensive and risky, especially if you might need to roll them over. Check campus emergency aid and credit unions first. This is general info, not legal advice.
Are payday loans legal in every state?
No. Some states ban or heavily limit them, and rules differ. Check your state regulator.
What is a payday loan rollover?
Extending the loan by paying a fee instead of the full balance, which can quickly increase total cost.
Where can I complain about a payday lender?
You can submit a complaint to the CFPB or your state attorney general or financial regulator.