First Car Loan as a College Student: Traps to Watch Out For
Getting your first car loan as a college student? Learn how loan terms, add-ons and dealer financing work, and what to compare before you sign anything.
“Nearly re-enrolled in English class while reading a lease.”
Theology · Scripture Cards
Open a scripture card
Already read and shared by 315 people.
 Listen to Him
Matthew 17:5
While he was still speaking, behold, a bright cloud overshadowed them. Behold, a voice came out of the cloud, saying, “This is my beloved…
Read this card
 He Revealed His Glory
John 2:11
This beginning of his signs Jesus did in Cana of Galilee, and revealed his glory; and his disciples believed in him.
Read this card
 I Am with You Always
Matthew 28:20
teaching them to observe all things that I commanded you. Behold, I am with you always, even to the end of the age.” Amen.
Read this card
 Wings like Eagles
Isaiah 40:31
but those who wait for Yahweh will renew their strength. They will mount up with wings like eagles. They will run, and not be weary. They…
Read this card
 Meant for Good
Genesis 50:20
As for you, you meant evil against me, but God meant it for good, to save many people alive, as is happening today.
Read this card
 Look and Live
Numbers 21:8-9
Yahweh said to Moses, “Make a venomous snake, and set it on a pole. It shall happen that everyone who is bitten, when he sees it, shall…
Read this card
 Until He Finds It
Luke 15:4, 6
“Which of you men, if you had one hundred sheep and lost one of them, wouldn’t leave the ninety-nine in the wilderness and go after the one…
Read this card
 I Am the Resurrection and the Life
John 11:25-26
Jesus said to her, “I am the resurrection and the life. He who believes in me will still live, even if he dies. Whoever lives and believes…
Read this card
Key Takeaways
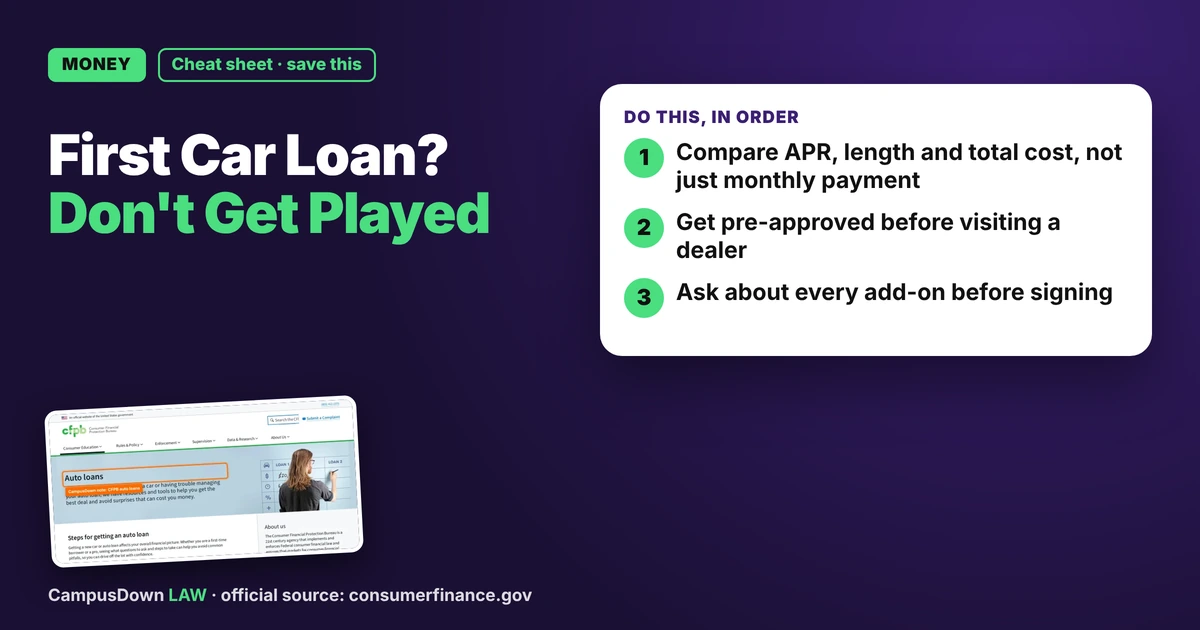
- Compare APR, length and total cost, not just monthly payment.
- Get pre-approved before visiting a dealer.
- Ask about every add-on before signing.
General information, not legal advice. Rules vary by state and can change; check the official sources linked in this guide.
I need a car to get to my job, my job helps pay for my apartment, and my apartment is where I'm currently eating rice for dinner. So yeah, I've looked into first car loan as a college student. Here's what I learned about not getting played.
Not financial or legal advice. Just research from someone who reads the CFPB site at night like it's a thriller.
Monthly payment isn't the whole story
A lower monthly payment can come from a longer loan, which can mean paying more total interest. The CFPB's auto loans page walks through comparing the total cost, not just the monthly number. Look at:
- APR (the yearly cost of borrowing)
- Loan length
- Total amount financed
- Fees and add-ons
Shop for financing before the dealer
You can often get pre-approved by a bank or credit union before stepping on the lot. Then the dealer has to beat that offer. Dealer financing isn't always bad, but having a comparison keeps things honest.
Watch the add-ons
Extended warranties, service contracts, GAP coverage and other extras may get rolled into your loan. Some can be useful, some are expensive, and many are optional. Ask what each one costs and whether it's required. If they say it's required, ask them to show you where.
Brain traps
Anchoring happens when the first number shapes everything after. Hyperbolic discounting is when "a car today!" beats "less debt later" in your head. And compound interest works against you on debt, so a longer loan can quietly cost more.
If you need a cosigner
A cosigner agrees to pay if you don't, and missed payments may affect their credit too. Talk honestly with them before asking.
Read before you sign
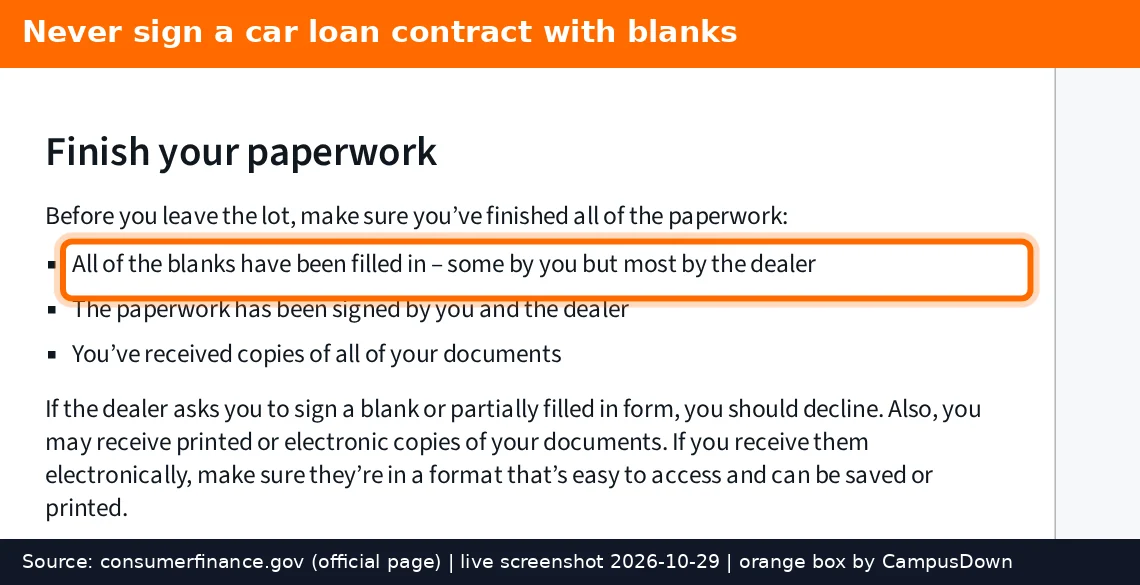
Don't sign blank or incomplete forms. Get copies of everything. If the deal changes after you leave the lot, like a call saying "financing fell through, come sign again," slow down and read the new terms carefully.
And honestly, a reliable cheap car beats a flashy car with a scary payment. Dates are impressed by showing up on time, not by your car payment. Probably.
Found this helpful? Share it with a friend who needs it.
Pick an app — it just sends the link, nothing else.
Frequently Asked Questions
Can a college student get a car loan?
Many can, sometimes with a cosigner or higher rate. Compare offers and the total cost. Not financial advice.
Is a longer car loan bad?
It can lower monthly payments but increase total interest. Compare total cost.
Are dealer add-ons required?
Many add-ons are optional. Ask what each costs and whether it's truly required.
Should I get pre-approved for a car loan?
Pre-approval from a bank or credit union can give you an offer to compare with dealer financing.