My First Student Loan Bill Arrived and I Can't Afford It. What Are My Options?
Can't afford student loan payments? Contact your servicer early, compare repayment plans on StudentAid.gov, understand pauses, and avoid default and scams.
“Nearly re-enrolled in English class while reading a lease.”
Theology · Scripture Cards
Open a scripture card
Already read and shared by 315 people.
 Twelve Baskets Left Over
John 6:11, 13
Jesus took the loaves, and having given thanks, he distributed to the disciples, and the disciples to those who were sitting down, likewise…
Read this card
 Look and Live
Numbers 21:8-9
Yahweh said to Moses, “Make a venomous snake, and set it on a pole. It shall happen that everyone who is bitten, when he sees it, shall…
Read this card
 The Rainbow Covenant
Genesis 9:13, 16
I set my rainbow in the cloud, and it will be a sign of a covenant between me and the earth. … The rainbow will be in the cloud. I will…
Read this card
 Water from the Rock
Exodus 17:6
Behold, I will stand before you there on the rock in Horeb. You shall strike the rock, and water will come out of it, that the people may…
Read this card
 Surely I Will Be with You
Judges 6:16
Yahweh said to him, “Surely I will be with you, and you shall strike the Midianites as one man.”
Read this card
 My Heart Rejoices in the Lord
1 Samuel 2:1-2
Hannah prayed, and said, “My heart exults in Yahweh! My horn is exalted in Yahweh. My mouth is enlarged over my enemies, because I rejoice…
Read this card
 I Am the Light of the World
John 8:12
Again, therefore, Jesus spoke to them, saying, “I am the light of the world. He who follows me will not walk in the darkness, but will have…
Read this card
 While He Was Still a Long Way Off
Luke 15:20, 22
“He arose and came to his father. But while he was still far off, his father saw him and was moved with compassion, and ran, fell on his…
Read this card
Key Takeaways
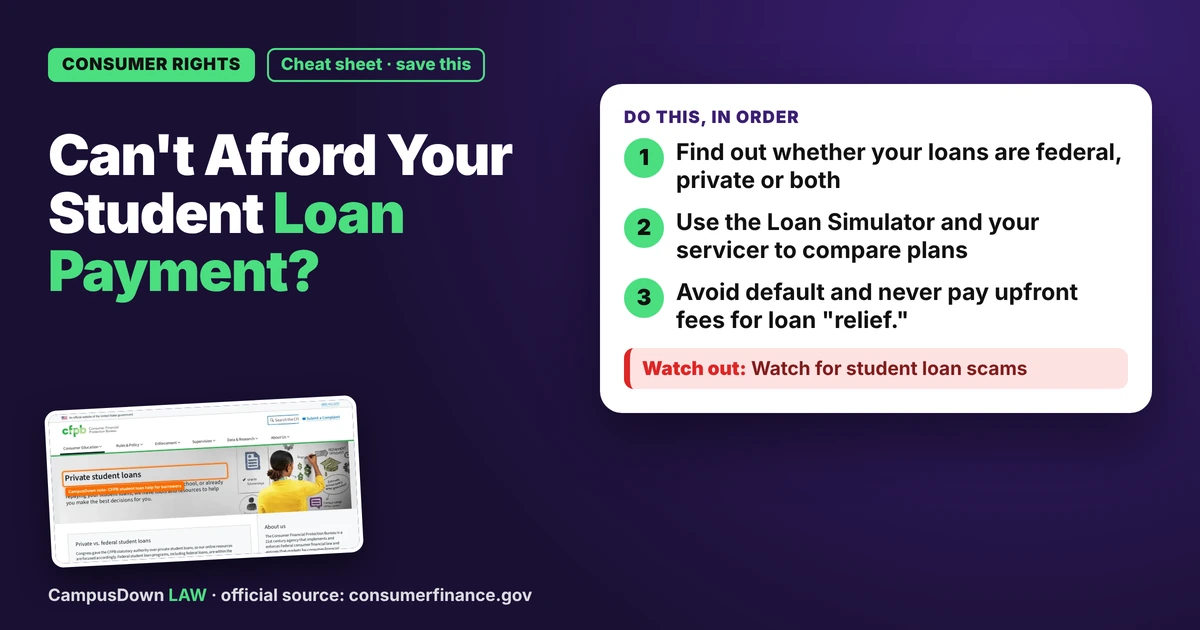
- Find out whether your loans are federal, private or both.
- Use the Loan Simulator and your servicer to compare plans.
- Avoid default and never pay upfront fees for loan "relief."
General information, not legal advice. Rules vary by state and can change; check the official sources linked in this guide.
The email subject line was cheerful: "Your first payment is due!" The amount was not cheerful. I did the math against my entry-level paycheck, rent and groceries, and it didn't work. If you can't afford your student loan payments, you're far from alone, and doing nothing is the one option that reliably makes it worse.
This is general information, not legal advice or financial advice. Federal student loan rules have changed a lot recently, so always check the current details on StudentAid.gov or with your servicer.
Step 1: Know what kind of loans you have
Federal and private student loans work very differently.
- Federal loans:* You can log in to StudentAid.gov to see your loans, your servicer, and your options. Federal loans generally have more flexible repayment options.
- Private loans:* These come from banks, credit unions, or other lenders. Options depend on your lender and your contract.
Many students have both. Write them all down: who the servicer or lender is, the balance, the interest rate, and the due date.
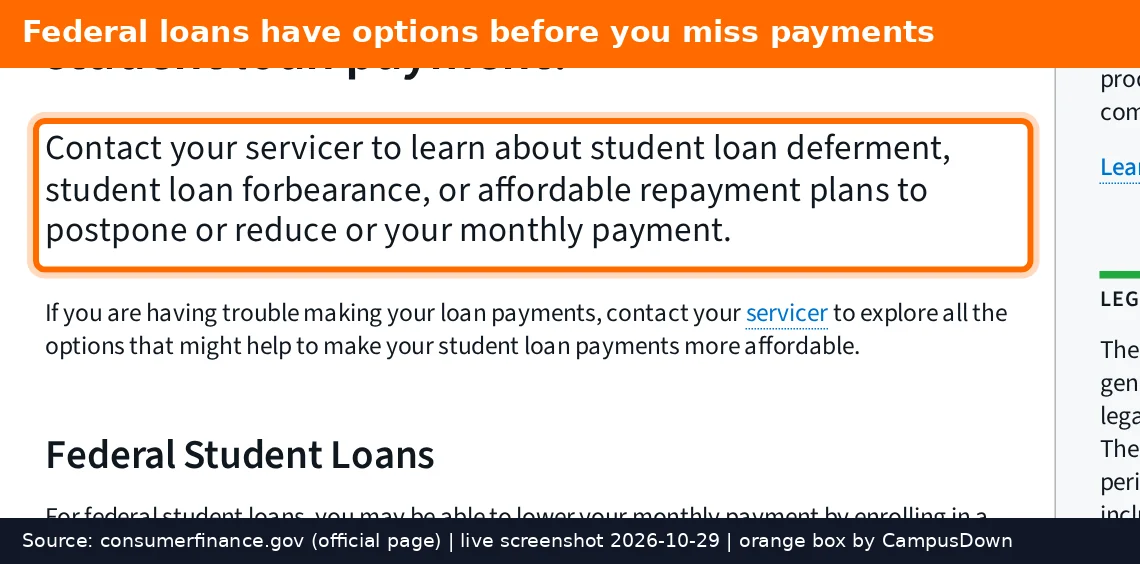
The Consumer Financial Protection Bureau has a student loan help page for borrowers, including what to ask your servicer. For federal plan details, StudentAid.gov's repayment page links to the Loan Simulator, which estimates payments under different plans using your actual loan information.
Step 2: Look at repayment plans
For federal loans, options may include plans based on your income, plans that stretch payments over a longer time, or a standard plan. Plan names and rules have shifted recently, so use the Loan Simulator and your servicer to see what's available to you today. For private loans, call your lender and ask directly about hardship options, temporary reduced payments, or extended terms.
Step 3: Short-term pauses (with caution)
Federal loans may offer deferment or forbearance in certain situations, like unemployment or economic hardship. These can give you breathing room, but interest may continue to grow, and that can increase what you owe overall. It's like compound interest working against you quietly in the background. Use pauses as a bridge, not a plan.
Step 4: Avoid default
If you miss payments for long enough, federal loans can go into default. Consequences can include damage to your credit score, collection costs, and the government taking money from tax refunds or wages. Even a reduced payment plan is better than silence. If you're already behind, contact your servicer about getting back on track.
Step 5: Look at your whole budget
A tough loan bill often means rethinking the budget. Mental accounting makes us treat money in separate "buckets," which can hide where it really goes. Looking at everything together, including subscriptions, can free up a surprising amount. Some employers also offer student loan help as a benefit; ask HR.
Legal stuff is easier with a friend. Send this to someone who could use it.
Pick an app — it just sends the link, nothing else.
Frequently Asked Questions
What happens if I can't pay my student loans?
For federal loans, contact your servicer to explore repayment plans, deferment, or forbearance. Missing payments for long enough can lead to default. This is general information, not legal advice.
How do I find out who my student loan servicer is?
For federal loans, log in to StudentAid.gov to see your loans and servicer. For private loans, check your lender's statements.
Does forbearance stop interest on student loans?
Often interest continues to grow during forbearance, which can increase your total balance.
Should I pay a company to lower my student loan payments?
Be cautious. Free help is available from your servicer and StudentAid.gov, and companies charging upfront fees may be scams.